Let’s face it – navigating the world of insurance can feel like diving into a deep, murky ocean. But fear not! Whether you’re a new resident or a lifelong Tar Heel, understanding how to secure the best insurance rates in North Carolina can transform the way you approach insurance shopping. With insight into the types of insurance available, factors influencing rates, and top providers in the state, you’re well on your way to making informed decisions.
In this guide, we’ll unravel the complexities of North Carolina’s insurance landscape using tactics and strategies that will make you think, “Why didn’t I know this before?” From uncovering hidden discounts to mastering negotiation skills, read on to discover how you can become an insurance-savvy consumer and lock in those coveted best rates.
Overview of Insurance Types in NC
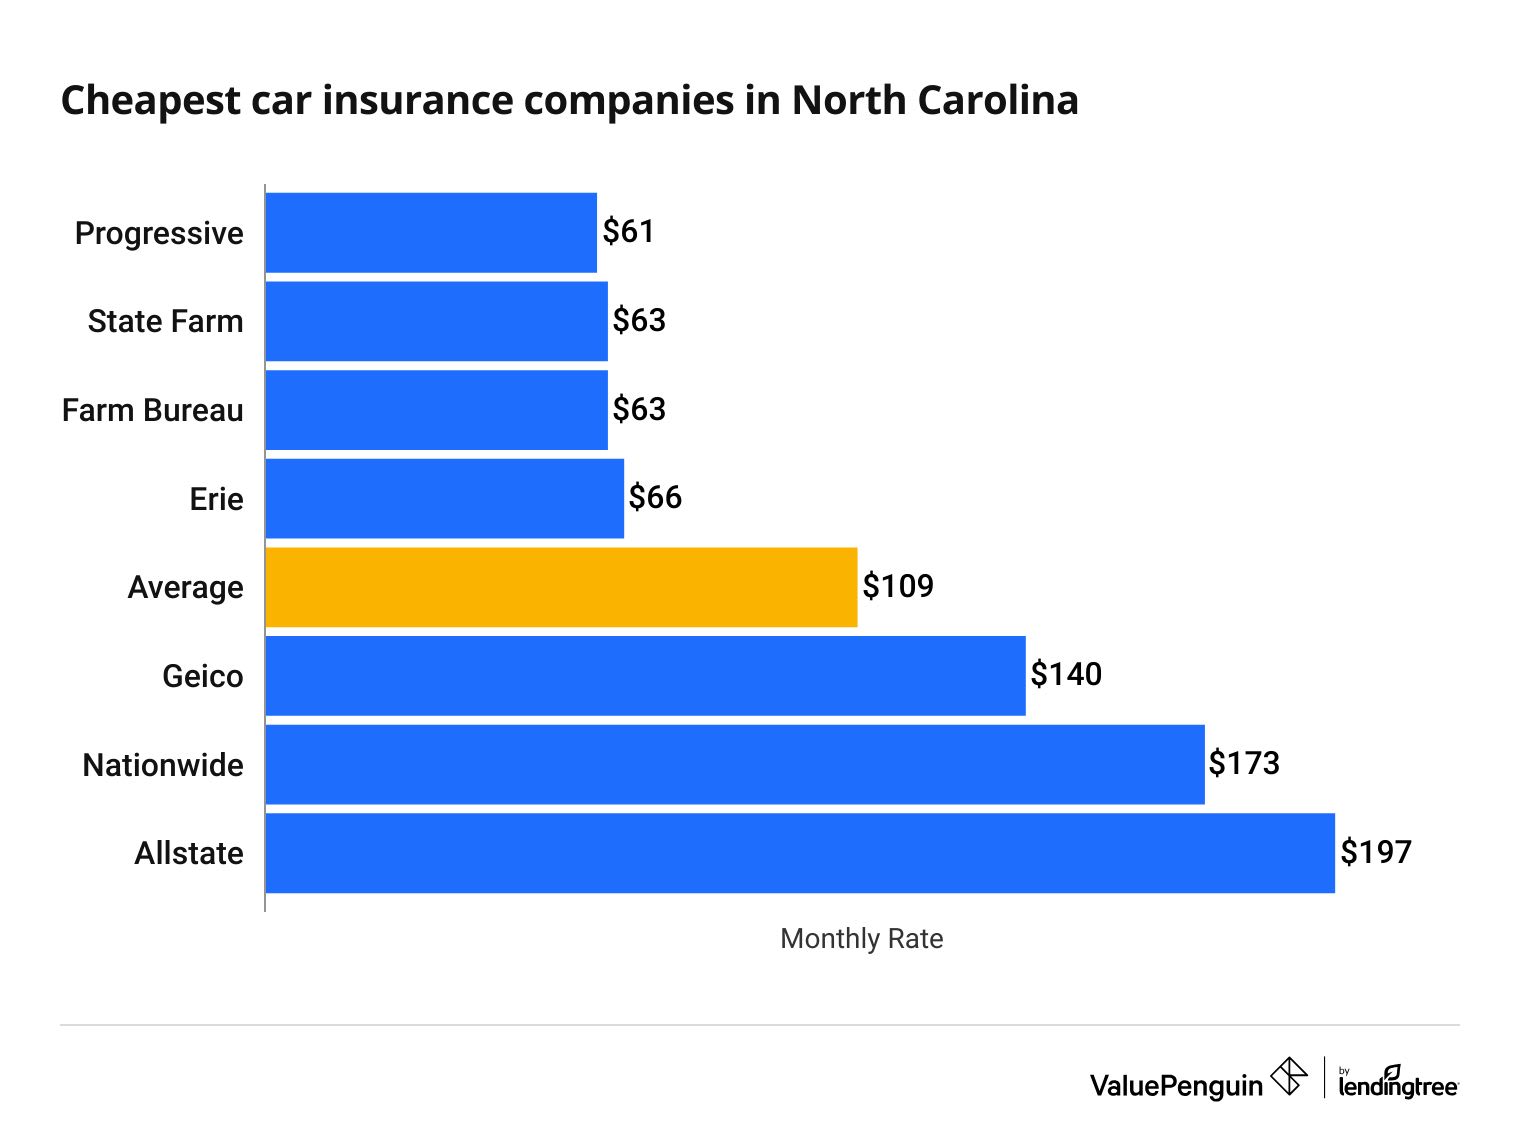
Did you know that North Carolina has some of the most competitive insurance rates in the country? But finding the right policy can feel like finding a needle in a haystack.
When it comes to insurance in North Carolina, you’ve got options galore. We’re talking auto, home, health, and life insurance. And they’re all regulated by the North Carolina Department of Insurance, ensuring you’re not just throwing your money into the wind.
Auto Insurance in North Carolina
Auto insurance is a must-have if you’re hitting the road. In fact, North Carolina law requires every driver to have at least liability coverage. But here’s the deal: you might want to consider more than just the minimum. Comprehensive and collision coverage can save your wallet if you find yourself in a fender bender.
- Liability Coverage: Covers damages to others in accidents you cause.
- Comprehensive Coverage: Protects against theft or damage not involving a crash.
- Collision Coverage: Covers your car’s repairs after an accident.
Pro Tip: Bundle your auto insurance with home insurance to score discounts!
Home Insurance in North Carolina
Your home is probably your biggest investment. So why not protect it? Home insurance in NC covers everything from fire to theft. BUT, if you live near the coast, look into additional flood insurance. The standard policy won’t cover water damage from hurricanes.
- Basic Homeowner’s Insurance: Covers the structure and personal property.
- Flood Insurance: Important for coastal areas, not included in standard policies.
- Liability Insurance: Protects you if someone gets injured on your property.
Health Insurance Options
Health insurance is not just a safety net; it’s a necessity. In North Carolina, you can choose from employer-provided plans, individual plans, or government programs like Medicaid and Medicare. Here is the deal: understanding your network and out-of-pocket costs can save you from surprise bills.
- Employer-Provided Plans: Often the most affordable option with shared costs.
- Individual Plans: Ideal for the self-employed or those without employer coverage.
- Government Programs: Available based on income and age requirements.
Life Insurance: Securing the Future
Life insurance isn’t just for the old and frail. It’s a smart move for anyone with dependents. North Carolina offers both term and whole life insurance. Term life is affordable and straightforward, while whole life builds cash value over time.
- Term Life Insurance: Provides coverage for a specific period.
- Whole Life Insurance: Offers lifetime coverage and a cash value component.
With all these choices, it’s clear that understanding your options is key to making the best decision for your circumstances. So, explore, compare, and secure the right policy for you and your family.
Factors Influencing Insurance Rates
Did you know that where you live could cost you hundreds more in insurance premiums? It’s true. In North Carolina, several factors can dramatically sway the rates you’ll pay for insurance.
From your zip code to your credit score, these elements aren’t just numbers—they’re key players in determining your insurance bill. Let’s break down how each factor impacts your rates and what you can do to optimize them.
Location Matters More Than You Think
Your location is one of the most significant factors affecting insurance rates. If you live in an urban area in North Carolina, you’re likely to pay higher premiums compared to someone living in a rural part of the state. Why? Because cities typically have higher traffic, leading to more accidents and claims.
Here’s the deal: moving just a few miles can sometimes swing your rates by a noticeable margin. So, if you’re looking to save, it might be worth considering a nearby area with lower rates.
Your Driving Record is Your Insurance Report Card
Having a clean driving record is like holding a golden ticket for lower insurance rates. If you’ve avoided speeding tickets and accidents, you’re probably enjoying some of the best rates around. But one fender bender? That could hike your premiums up.
Pro Tip: Consider taking a defensive driving course. Some insurers offer discounts for completing these programs.
It’s not just about being accident-free. Speeding tickets and other violations can also add up, leading insurers to see you as a higher risk.
Credit Score: The Silent Rate Killer
Your credit score might not be the first thing that comes to mind when you think of car insurance, but it plays a crucial role. Insurers use it to predict your likelihood of filing a claim. A low score can mean higher premiums, while a high score can earn you discounts.
Think about it: maintaining a good credit score doesn’t just help with loans and mortgages—it can directly lower your insurance costs too. Keep an eye on your score and improve it for easier savings.
Comparing Factors Across Insurance Types
Let’s see how these factors influence different types of insurance in North Carolina:
| Factor | Auto Insurance | Home Insurance | Health Insurance |
|---|---|---|---|
| Location | High Impact | Moderate Impact | Low Impact |
| Driving Record | High Impact | None | None |
| Credit Score | Moderate Impact | High Impact | Low Impact |
As you can see, the same factor can influence various insurance types differently. By understanding these nuances, you can better navigate the insurance landscape in North Carolina.
Top Insurance Providers in NC
Think you’re paying too much for insurance? You might be right. North Carolina’s insurance market is bustling with options, but sifting through them can be overwhelming.
Let’s break it down. Some companies stand out for their unique offerings and customer service. Here is the deal: choosing the right provider can save you not only money but also give you peace of mind.
Leading Companies Offering Insurance in North Carolina
When it comes to choosing the best insurance provider in NC, you’ve got choices. From giants like State Farm to niche players, there’s something for everyone.
- State Farm: Known for their comprehensive coverage options and a vast agent network, they prioritize personalized service.
- Nationwide: Offers unique coverage options like pet insurance bundled with home insurance.
- Allstate: Famous for customizable policy options and excellent customer service.
- Progressive: They shine with competitive rates and strong online tools for customers.
- GEICO: Provides a user-friendly mobile app and some of the lowest rates in the state.
How These Providers Stack Up
Choosing an insurance provider in NC isn’t just about rates. It’s about finding the right fit for your needs. Check out this comparison table to see how they align with what you’re looking for:
| Provider | Coverage Options | Customer Service | Rates |
|---|---|---|---|
| State Farm | Home, Auto, Health, Pet | Personalized agents | Moderate |
| Nationwide | Auto, Home, Pet | Good | Competitive |
| Allstate | Auto, Home, Renters | Excellent | Higher |
| Progressive | Auto, Commercial, Motorbike | Solid online support | Low |
| GEICO | Auto, Motorcycle, RV | Efficient apps | Very low |
Pro Tip: Always compare at least three providers to ensure you’re getting the best deal.
Strategies to Secure the Best Insurance Rates
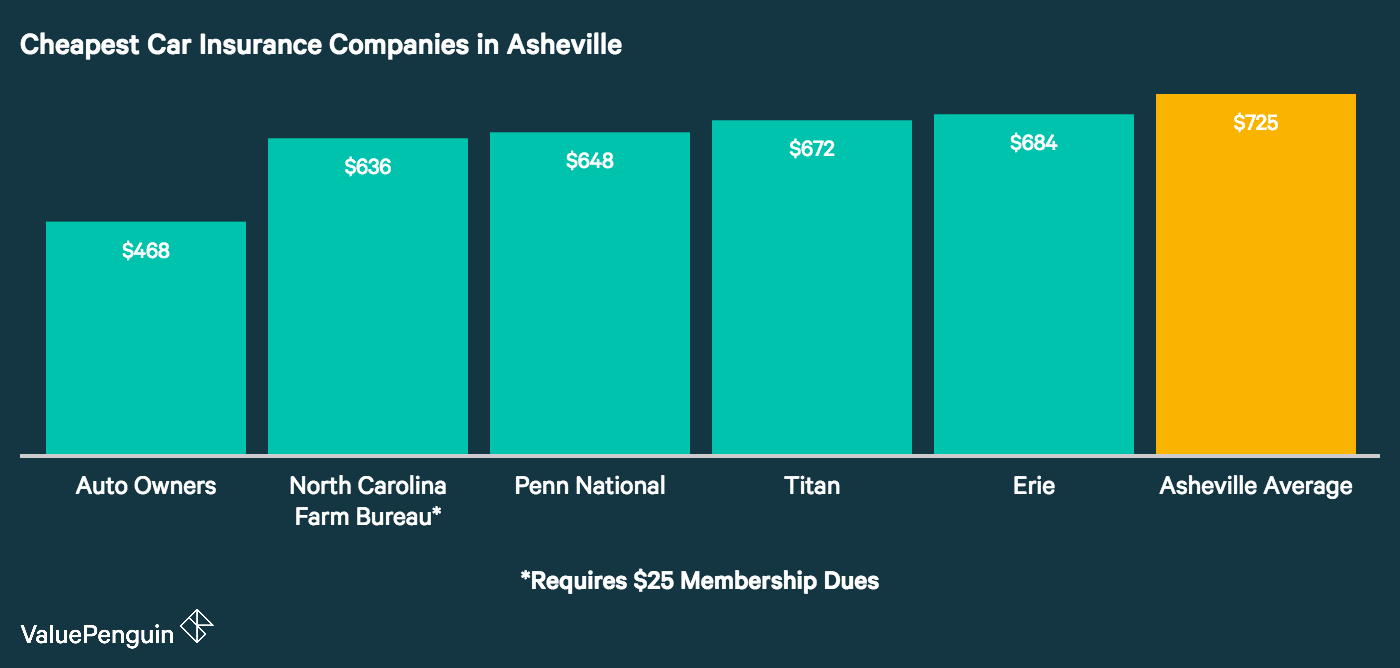
Think you’re paying too much for insurance in NC? You’re probably right. But don’t worry, I’ve got you covered with some killer strategies to slash those premiums.
From shopping around to bundling policies, these tactics will help you secure the best rates without sacrificing coverage. Let’s dive in and uncover how you can save.
Shop Around Like a Pro
If you’re settling for the first quote you get, you’re leaving money on the table. Shopping around is crucial. This means comparing at least three different insurance providers. Each company has its own method of calculating rates, and small differences can mean big savings for you.
- Use comparison websites to get initial quotes quickly.
- Follow up with a phone call to negotiate directly.
- Don’t shy away from lesser-known providers; they might offer killer deals.
Harness the Power of Negotiation
You can haggle with your insurance company more than you think. When you get a quote, it’s not set in stone. Negotiating can save you hundreds, if not thousands, over time.
Here’s what you do: Ask if they can beat a competitor’s rate. Often, they’ll throw in a discount just to keep you. Also, inquire about any hidden discounts. You might be surprised at what’s available if you just ask.
Pro Tip: Always have a competing quote in hand before you start negotiating for the best leverage.
Bundle Up for Discounts
Insurance companies love it when you bundle your home, auto, and other policies together. They love it so much, they usually offer a sweet discount.
Here’s the deal: Bundling can save you up to 25% off your premiums. It’s a win-win. You get better service coordination and a hefty cut on your rates.
- Contact your current insurance provider to see what bundles they offer.
- Evaluate whether the bundle gives you enough savings compared to separate policies.
- Don’t forget to reassess this every year. The best deal this year might not be the best next year.
Importance of Comparing Insurance Quotes
Did you know that by not comparing insurance quotes, you could be leaving hundreds of dollars on the table? It’s true. Many people often stick to their current provider without checking if they’re getting the best deal.
But here’s the deal: comparing insurance quotes before purchasing a policy can save you a ton of money. When you compare, you’re not just looking at price. You’re considering coverage, customer service, and policy terms. This ensures you get the best value for your hard-earned money.
Benefits of Comparing Insurance Quotes
By comparing quotes, you gain a better understanding of the market. You’re no longer at the mercy of a single provider. Instead, you have the power to choose from multiple options and find a policy that perfectly suits your needs and budget. When you compare quotes, you can find hidden fees and avoid policies that seem cheap upfront but are costly in the long run.
“The biggest savings often come from comparing what others are offering.”
Step-by-Step Guide to Obtaining and Evaluating Quotes
Ready to find the best rates? Here’s your game plan:
- Start by listing your insurance needs and what coverage you require.
- Use online comparison tools to pull quotes from multiple providers.
- Analyze each quote carefully, considering both price and coverage details.
- Contact the most promising providers for any clarifications or additional discounts.
- Make your decision based on the best balance of cost, coverage, and service.
Useful Tools and Resources for Comparing Insurance Rates
Comparing quotes doesn’t have to be difficult. Here are some tools and resources you can use:
- Insurance comparison websites like Compare.com and The Zebra.
- Online calculators to estimate potential savings.
- Consumer review sites for insights on customer service and claim handling.
- State insurance department websites for regulatory information.
“Pro Tip: Always check for discounts based on your profession, membership affiliations, or safe driving record.”
By leveraging these tools, you’ll be better equipped to make an informed decision. Remember, the goal is not just to find the cheapest quote, but the one that offers the best overall value.
Case Studies on Insurance Savings
Ever wondered how some people manage to save a ton on their insurance costs while others seem to pay through the nose? You’re about to dive into real-life examples of individuals and families who slashed their insurance expenses.
These case studies will reveal the strategies they used to achieve significant savings. From bundling policies to loyalty discounts, there’s a lot you can learn and apply to your situation.
Family Bundles: The Johnsons’ Strategy
The Johnsons were paying nearly $5,000 a year on car and home insurance. That was until they decided to bundle their policies with one provider. They managed to cut costs by 20%! By sticking to one insurance company, you can unlock bundle discounts that many don’t even know exist.
Pro Tip: Always ask about bundling discounts. It’s like hitting two birds with one stone—except the second bird is savings!
Playing the Loyalty Card: How Michael Saved $800
Michael had been with the same insurance provider for over a decade. Most people think loyalty doesn’t pay off, BUT Michael discovered that it does. He negotiated with his provider and managed to save $800 annually by leveraging his long-term customer status.
Here is the deal: Loyalty can translate into bargaining power. Don’t just renew your policy; use your history to negotiate better rates.
Shopping Around: A Game Changer for Sarah
Sarah was paying $1,200 for her health insurance. After comparing rates from multiple providers, she found a similar policy for just $900. That’s a 25% saving!
Never assume you’re getting the best rate—providers often change their offerings, and what was competitive last year might not be the same today.
Hypothetical Impact: Applying These Strategies
Imagine a family spending $3,000 on auto insurance. By bundling with home insurance, they save 15%, bringing costs down to $2,550. If they also negotiate a loyalty discount of 5%, their total drops to $2,422.50. That’s a total saving of $577.50—money back in their pockets!
Always question current rates. The market evolves, and so should your strategy.
Summary
Armed with newfound knowledge and actionable strategies, you’re now ready to tackle the insurance market with confidence. Remember, the key to securing the best insurance rates in NC lies in being proactive, curious, and strategic. By comparing quotes and leveraging your unique circumstances, you can transform your insurance experience from a daunting task into a rewarding journey. So, go forth and conquer the world of insurance with the expertise you’ve gained here!
FAQ Section
What types of insurance are available in North Carolina?
In North Carolina, you can find a range of insurance options including auto, home, health, and life insurance. Each type serves different needs and offers varying levels of coverage.
How does location affect insurance rates in NC?
Your location can significantly impact your insurance rates due to factors like crime rates, accident statistics, and natural disaster risk in your area.
What are some strategies to lower my insurance rates in North Carolina?
To lower your rates, consider bundling policies, maintaining a clean driving record, improving your credit score, and exploring available discounts.
Why is it important to compare insurance quotes?
Comparing quotes is crucial as it helps you identify the best coverage options at competitive rates, ensuring you get the most value for your money.
Who are the top insurance providers in North Carolina?
Some of the leading insurance providers in NC include State Farm, Nationwide, and Allstate, each offering unique benefits and coverage options.
