Hey there, car owners! If you’re cruising around the Bay State, you might be wondering, “How much is auto insurance in Massachusetts?” Well, buckle up, because we’re about to take a deep dive into the ins and outs of auto insurance in this historic state. Whether you’re a first-time driver or a seasoned road warrior, understanding the nuances of insurance can save you big bucks and a ton of headaches.
Imagine having the peace of mind that comes with knowing you’re fully protected on the road. With a plethora of coverage options, discounts, and consumer protections, Massachusetts is a unique landscape in the world of auto insurance. Ready to navigate the twists and turns of this essential car ownership topic? Let’s get started!
Overview of Auto Insurance in Massachusetts
Did you know that without the right coverage, you could be driving illegally in Massachusetts? This state has some of the most stringent auto insurance laws in the U.S. Let’s dive into what you need to know.
Massachusetts law requires all drivers to carry a minimum level of auto insurance. But simply meeting the minimum isn’t always enough. Factors like your age, driving history, and even your zip code can significantly impact your rates.
Key Factors Affecting Auto Insurance Rates
Auto insurance in Massachusetts isn’t one-size-fits-all. Your rates are affected by a mix of personal and geographical factors. For instance, younger drivers often face higher premiums due to their relative inexperience. Meanwhile, living in a densely populated area might also hike up your costs due to the increased likelihood of accidents.
Here’s the deal: If your driving record is spotless, you’re likely to enjoy lower rates. But, any history of accidents or violations can have the opposite effect.
Types of Coverage Options Available
Massachusetts offers a range of auto insurance coverage options beyond the legal minimums. Commonly, drivers opt for additional collision and comprehensive coverage to protect against more than just accidents. But don’t overlook the importance of uninsured/underinsured motorist coverage—it’s like having a safety net!
Pro Tip: Always shop around and compare quotes from multiple insurers. This simple step can save you hundreds annually.
Remember, while it might be tempting to go with the bare minimum, investing in robust coverage can offer peace of mind and financial security.
Factors Influencing Insurance Costs
Think your car insurance premiums are too high? You might be surprised by what actually drives up the cost. There are multiple factors at play.
From your age to your zip code, a variety of elements influence what you pay for auto insurance in Massachusetts. While some factors are under your control, like your driving record, others, such as your geographical location, are not. Here’s the deal: understanding these factors can help you save money.
Personal Factors That Affect Insurance Rates
Let’s dive into the personal factors first. Your age is a major player. Drivers under 25 typically pay more. Why? They’re statistically more likely to get into accidents. But as you age, expect those rates to drop as long as you maintain a clean driving record.
Now, consider your driving history. If you’ve had a couple of fender-benders or a speeding ticket, your rates will be higher. Insurance companies see that as risky behavior. Keep your record clean, and you’ll likely see better rates.
Vehicle and Its Impact on Premiums
Your car type is another biggie. Driving a high-performance sports car? Expect to pay top dollar. Insurers view these cars as a higher risk for accidents. On the flip side, a mid-range sedan won’t break the bank.
Here’s another angle: safety features. Cars equipped with advanced safety systems can lower your premiums. So, it might be time to consider those add-ons if you’re in the market for a new vehicle.
Geographical Variations in Massachusetts
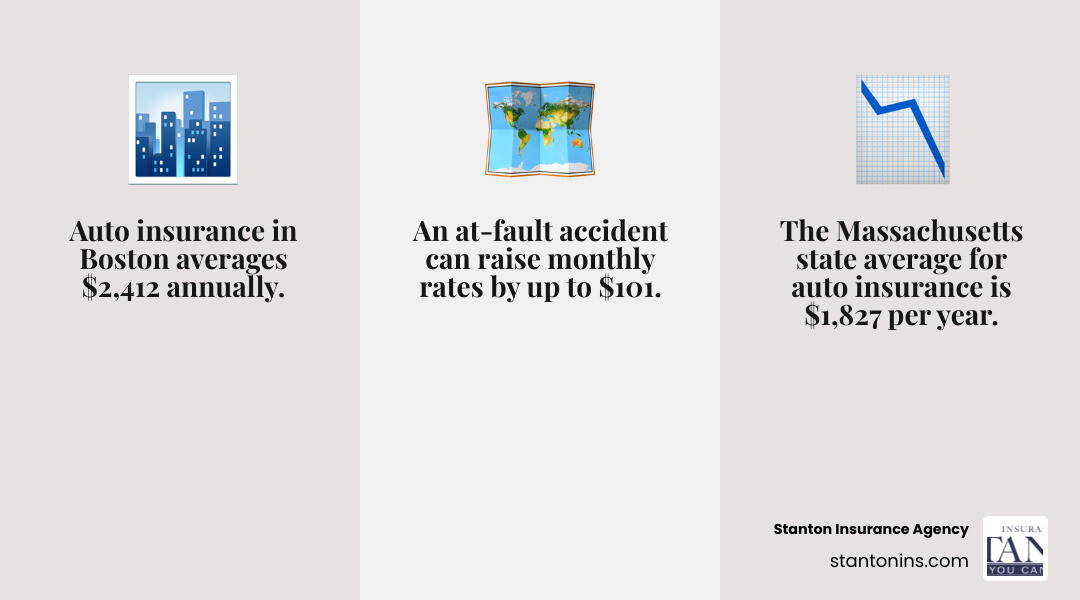
Did you know where you live can affect your insurance rates? It’s true. Urban areas like Boston have higher premiums compared to rural spots. Why? More traffic, more accidents, and higher theft rates.
Here’s a quick comparison:
| Location | Average Annual Premium |
|---|---|
| Boston | $1,500 |
| Springfield | $1,200 |
| Amherst | $1,000 |
Living in a high-risk area doesn’t mean you’re stuck paying sky-high rates. You can offset this by keeping your driving record spotless and choosing a vehicle with excellent safety ratings.
Pro Tip: Compare rates from different insurers to find the best deal in your area.
Average Cost of Auto Insurance

Did you know that the average cost of auto insurance in Massachusetts is higher than the national average? If you’re a Massachusetts resident, you might be shelling out more than you think.
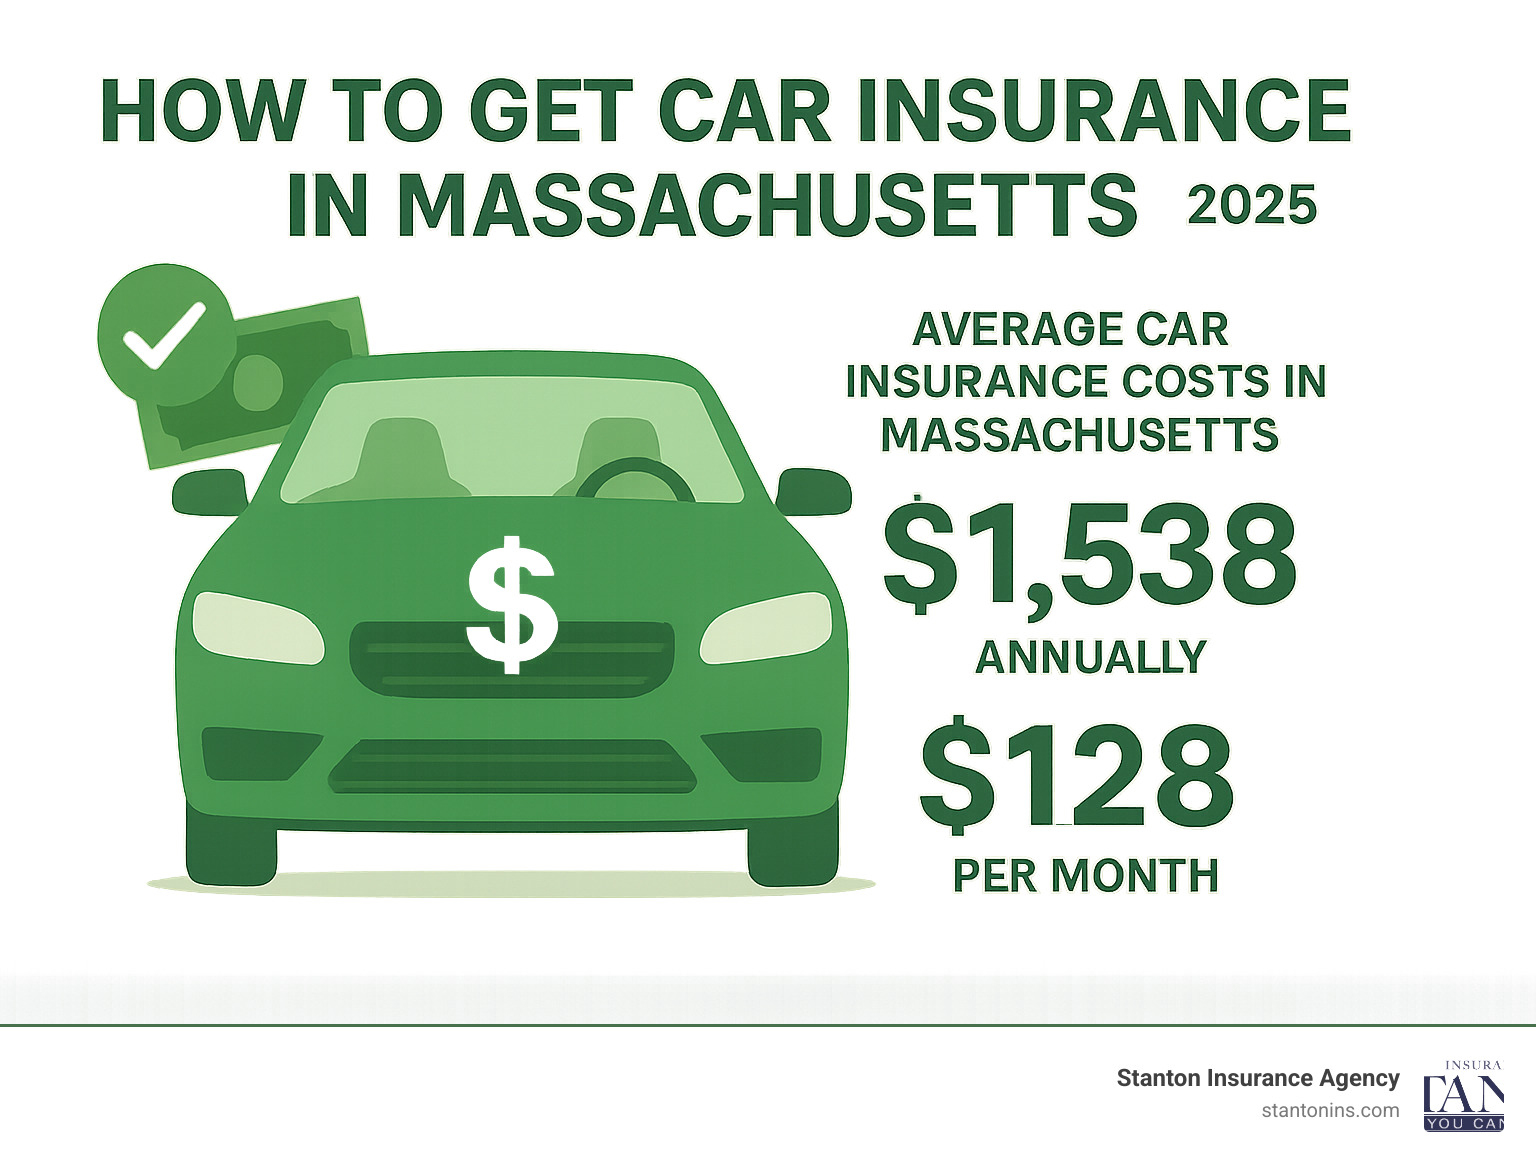
Let’s break it down. The typical cost in Massachusetts is around $1,460 per year. BUT this number can vary drastically depending on where you live in the state.
Cost Differences Across Major Cities
Auto insurance rates aren’t uniform across Massachusetts. For instance, living in Boston could set you back more compared to Springfield. Why? Because urban areas often have higher rates of accidents and theft.
| City | Average Annual Cost |
|---|---|
| Boston | $1,780 |
| Springfield | $1,320 |
| Worcester | $1,400 |
| Cambridge | $1,650 |
As you can see, location plays a huge role in determining how much you’ll pay. So, if you’re considering a move, factor this into your budget.
Insurance Costs Based on Coverage Levels
Your coverage level and deductible significantly affect what you’ll pay. Want to save a few bucks? Opt for higher deductibles. But remember, this means more out-of-pocket expenses if you file a claim.
| Coverage Level | Average Cost with $500 Deductible | Average Cost with $1,000 Deductible |
|---|---|---|
| Minimum Coverage | $1,100 | $950 |
| Standard Coverage | $1,460 | $1,300 |
| Full Coverage | $1,800 | $1,620 |
Here’s the deal: choosing the right balance for your financial situation and risk tolerance is key.
Pro Tip: If you drive an older car, you might consider dropping collision coverage to save money.
Discounts and Savings Opportunities
Think you’re paying too much for your auto insurance? You might be right. The good news is Massachusetts drivers have a host of discounts at their disposal to cut those costs.
These savings aren’t just for the lucky few. By knowing where to look and what to ask for, you can significantly reduce your premiums without sacrificing coverage.
Unlocking Common Discounts
Many insurers offer a range of discounts to help you save. From safe driving to bundling multiple policies, there are plenty of ways to keep your costs down.
For instance, if you’ve got a clean driving record, you’re likely to qualify for a safe driver discount. And if you’re willing to take a defensive driving course, you could save even more.
How to Qualify for Discounts
Qualifying for discounts isn’t as hard as it seems. Here’s the deal: the more you bundle, the more you save. If you combine your auto insurance with a homeowner’s or renter’s policy, you can snag a significant discount.
Maintaining a clean driving record is another ticket to savings. Insurers love safe drivers and often reward them with lower rates. Plus, if you install anti-theft devices in your vehicle, you could see a reduction in your premium.
Pro Tip: Always ask your insurer about available discounts. You’d be surprised at how many savings opportunities go unnoticed!
Top Tips for Maximizing Insurance Savings
Ready to save? Start with these actionable tips:
- Shop around and compare rates from multiple insurers.
- Bundle your auto insurance with other policies for a discount.
- Maintain a clean driving record to qualify for safe driver savings.
- Consider increasing your deductible to lower your premium.
- Ask about low mileage discounts if you don’t drive much.
Regulations and Consumer Protections
Did you know Massachusetts has some of the most stringent auto insurance regulations in the U.S.? That’s right. These regulations are designed to protect you and ensure fair pricing.
The state mandates a minimum coverage level for all drivers. This includes liability, personal injury protection, and more. The goal? Keep you covered in any situation. But here’s the deal: Massachusetts uses a “no-fault” system, meaning your insurance pays for your own injuries, regardless of who caused the crash.
Understanding Massachusetts Insurance Requirements
In Massachusetts, you’re required to have minimum liability coverage of $20,000 per person and $40,000 per accident. Sound low? Maybe. But it’s the law. You also need $8,000 in personal injury protection. These figures are non-negotiable and are set to ensure every driver has some level of protection.
Consumer Rights and Protections
Ever feel like insurance companies hold all the cards? Not in Massachusetts. The state has strong consumer protection laws aimed at ensuring fairness. If an insurer tries to pull a fast one, Massachusetts’ Division of Insurance has your back. They enforce rules that require insurers to handle claims promptly and fairly.
Filing Complaints or Disputes
If you’re stuck in a dispute with your insurer, Massachusetts makes it easy to file a complaint. Step #1: Contact the Consumer Services Section of the Division of Insurance. They’ll guide you through the process. Step #2: Fill out a complaint form detailing your issue. Step #3: Let the state’s insurance experts take it from there. They’ll investigate and mediate on your behalf.
Pro Tip: Always keep detailed records of your communication with your insurer. This can be invaluable if you need to escalate your complaint.
Choosing the Right Insurance Provider
Did you know that picking the wrong auto insurance can cost you hundreds more each year? It’s not just about the price; it’s also about the service, coverage, and peace of mind.
Choosing the right insurance provider in Massachusetts involves more than just comparing rates. You need to weigh features, customer service, and claims satisfaction. Let’s dive into the specifics.
Key Criteria for Selection
When you’re on the hunt for the right provider, focus on a few key areas. First, look at the financial stability of the company. You want an insurer who’ll be around when you need them. Also, consider the coverage options they offer. Do they meet your needs now and potentially in the future?
- Check the company’s financial ratings through agencies like A.M. Best.
- Evaluate the broadness of coverage offerings—liability, collision, and comprehensive should be on your checklist.
- Assess the provider’s reputation—look for customer reviews and claims satisfaction ratings.
Comparison of Leading Providers
How do the top providers stack up? Let’s take a quick look at some of the most popular options in Massachusetts. Remember, it’s not just about the cheapest option, but the one that gives you the best value for your money.
| Provider | Key Features | Customer Rating |
|---|---|---|
| Provider A | 24/7 claims service, New car replacement | 4.5/5 |
| Provider B | Multiple discounts available, Roadside assistance | 4.3/5 |
| Provider C | User-friendly mobile app, Accident forgiveness | 4.6/5 |
Evaluating Customer Service and Claims Satisfaction
Don’t underestimate the power of customer service. It’s the backbone of any good insurance experience. Here’s how you can evaluate it effectively.
- Read online reviews from multiple sources to get a balanced view.
- Check out the company’s response time—how quickly do they resolve claims?
- Test their customer service by calling or chatting online to see how they handle inquiries.
Pro Tip: Always check the claims satisfaction score. A provider may offer attractive premiums, but if their claims process is a nightmare, it’s not worth it.
Last Word
And there you have it—the roadmap to understanding how much auto insurance costs in Massachusetts. By knowing the factors that influence your rates and the discounts available, you’re already miles ahead in the insurance game. Empower yourself with this knowledge, choose the right provider, and drive with confidence knowing you’re well-protected. Safe travels!
Frequently Asked Questions
What are the minimum auto insurance requirements in Massachusetts?
In Massachusetts, drivers must carry a minimum of 20/40/5 coverage, which includes $20,000 per person and $40,000 per accident for bodily injury, and $5,000 for property damage.
How do age and driving record affect my insurance rates?
Younger drivers and those with a poor driving record often face higher premiums. Conversely, a clean driving record and more years of driving experience can help reduce rates.
Are there geographical variations in insurance costs within Massachusetts?
Yes, insurance costs can vary based on where you live. Urban areas like Boston tend to have higher rates compared to rural regions due to factors like traffic density and accident rates.
What types of discounts are available to Massachusetts drivers?
Common discounts include multi-policy discounts, safe driver discounts, and discounts for vehicles with safety features. It’s worth checking with your provider for specific discounts you may qualify for.
How can I file a complaint against my insurance provider in Massachusetts?
If you have an issue with your insurance provider, you can file a complaint with the Massachusetts Division of Insurance. They provide resources and support for resolving disputes.
